


12 common mistakes that could put your home cover at risk
What Could Invalidate Your Home Insurance?
Home insurance is something many of us only think about when we need it. If your home is affected by fire, flooding, theft or another insured event, you want to know your policy is there to respond.
However, problems can arise if information is inaccurate, circumstances change or certain policy conditions are not met.
That does not mean every mistake automatically invalidates your insurance. Depending on what has happened and the wording of your policy, a claim could be reduced or declined, particular cover could be restricted or, in more serious circumstances involving misrepresentation, the policy itself could be affected.
Here are 12 common issues worth checking.
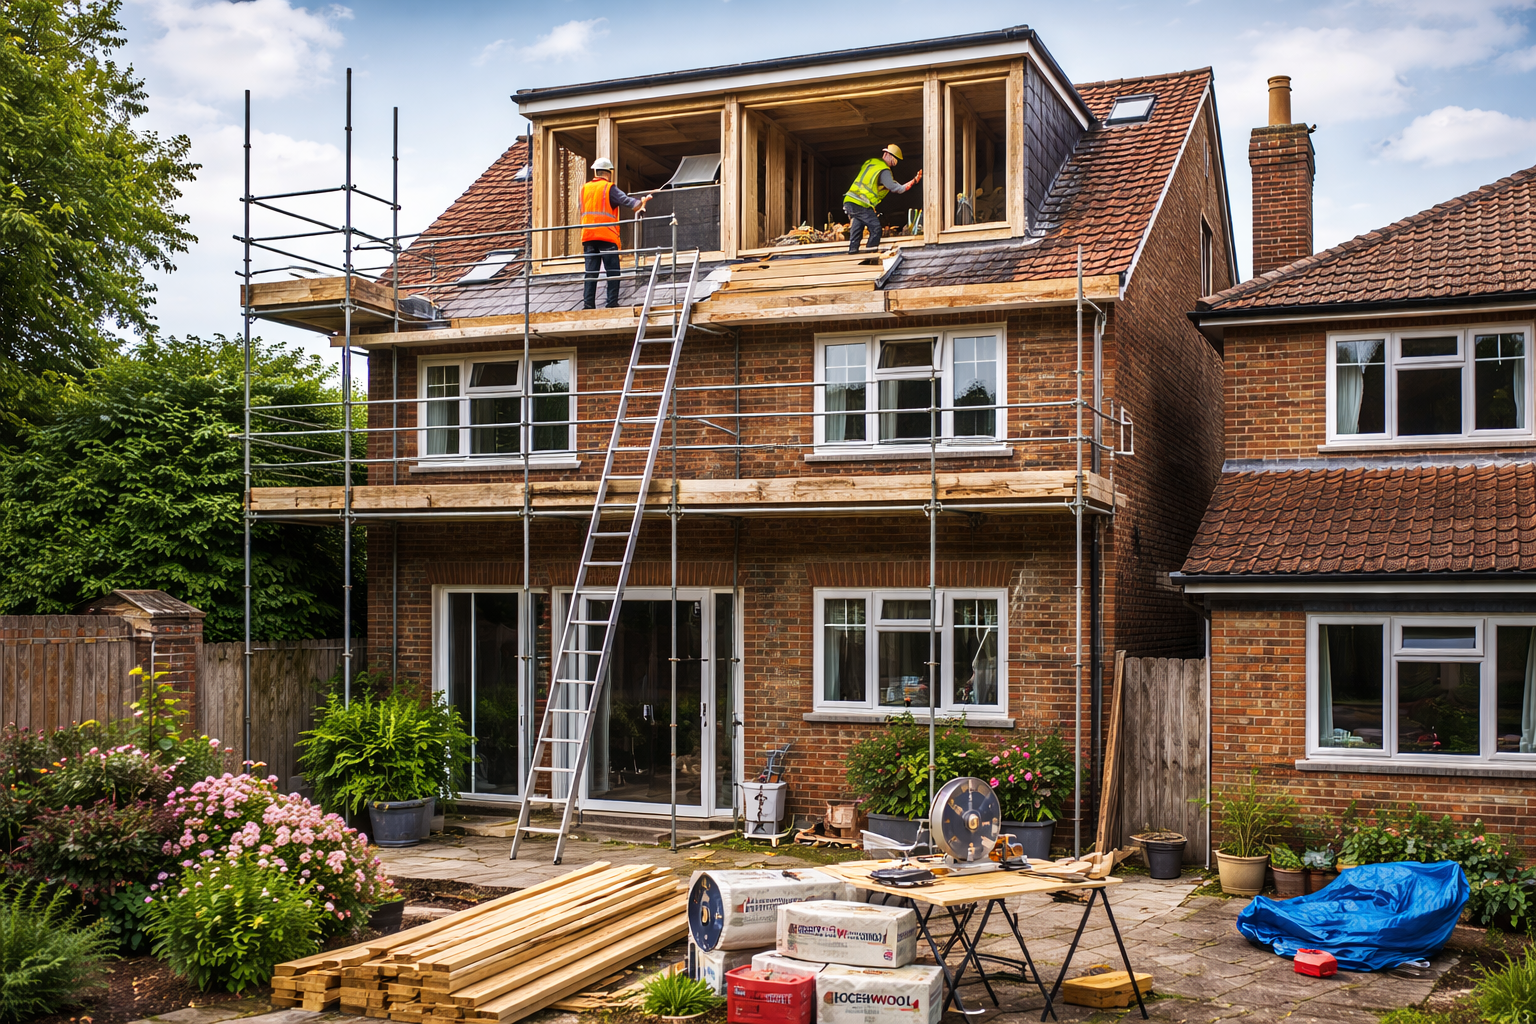
1. Starting building work without checking your insurance
Planning an extension, loft conversion, major renovation or structural alteration?
Before work begins, check whether your insurer needs to know.
Substantial building work can change the risks associated with your home. Parts of the property may be exposed, walls could be removed, security arrangements may change and the property might even become temporarily uninhabitable.
Requirements vary between policies, so speak to your insurer or broker before significant work starts rather than assuming your existing cover will continue unchanged.
It is also worth checking what insurance your builder or contractor has in place.
2. Leaving your home unoccupied for too long
If your property is going to be empty for an extended period, check your policy.
Many home insurance policies restrict certain types of cover once a property has been unoccupied for a specified period, commonly 30 or 60 days. The exact period and definition of ‘unoccupied’ depend on the individual policy.
This could be relevant if you:
Take an extended holiday
Spend a prolonged period in hospital
Work away from home
Move out during renovations
Leave the property empty while waiting to sell or move
Restrictions can apply to risks such as theft, malicious damage or escape of water, so always check what your policy requires.
3. Allowing maintenance problems to develop
Home insurance is generally intended to cover insured events rather than routine maintenance or gradual deterioration.
Long-standing problems such as deteriorating roofs, untreated damp, worn seals or poorly maintained guttering may not be covered in the same way as sudden accidental damage.
If you become aware of a problem, dealing with it promptly can help prevent further damage and reduce the risk of difficulties with a later claim.
4. Running a business from home without checking your cover
Working from home does not necessarily mean you are running a business from your property.
However, your insurance requirements could change if you:
Store business stock at home
Have customers or clients visiting
Keep specialist equipment at the property
Employ people from your home
Run a salon, workshop or other customer-facing business
If your use of the property changes, check whether your existing home insurance remains suitable or whether additional business cover is required.
5. Failing to meet security requirements
Your policy may contain requirements relating to locks, alarms or other security measures.
These are particularly important if the insurer has applied a specific security condition to your policy.
If you have told your insurer that certain locks, alarms or other security devices are fitted, make sure that information remains accurate.
Leaving the property unsecured could potentially affect a theft claim, but it does not automatically mean every claim will be rejected. The circumstances and policy wording will matter.
6. Deliberately damaging the property
Insurance is intended to protect against unexpected events rather than damage deliberately caused by the policyholder.
Policies commonly exclude deliberate or intentional acts.
However, situations involving deliberate damage by another household member can be more complicated, so the exact circumstances and wording of the policy will matter.
7. Providing incorrect or incomplete information
When taking out, renewing or changing your home insurance, it is important to answer the insurer’s questions accurately.
Relevant information could include:
The type and construction of your property
Who normally lives there
Previous claims
How the property is used
Whether it is usually occupied
Renovations or building work where you are asked about them
The value of belongings that need to be declared
Under consumer insurance law, customers must take reasonable care not to make a misrepresentation.
If incorrect information comes to light, the outcome will depend on factors such as whether the error was careless or deliberate and what the insurer would have done if it had been given the correct information.
8. Being underinsured
Having too little cover can cause problems when you make a claim.
For buildings insurance, the amount insured may need to reflect the cost of rebuilding your home rather than its market value, depending on how your policy is arranged.
For contents insurance, you should also consider the total replacement value of your belongings.
If your sum insured is too low, an insurer may not pay a claim in full and, depending on the circumstances and policy terms, could potentially decline it altogether.
Also check whether expensive individual items need to be listed separately because they exceed your policy’s single-item limit.
9. Taking in a lodger or renting out your property
Changing who lives in your home can alter the risk being insured.
This can include:
Taking in a lodger
Renting out a room
Letting the entire property
Offering short-term holiday accommodation
A standard home insurance policy may not be designed for every type of rental or letting arrangement.
Check with your insurer or broker before making a change so you know whether your existing cover remains suitable.
10. Forgetting to review your policy when circumstances change
Homes and households rarely stay exactly the same.
You may carry out improvements, buy expensive possessions, set up a home office or change who lives at the property.
Not every change needs to be reported immediately, so check your policy rather than assuming that it does.
However, it is worth reviewing your insurance after any significant change to make sure:
Your sums insured remain sufficient
High-value possessions are covered appropriately
Your insurer’s information remains accurate
The way your property is used still fits the policy
Renewal is a useful opportunity to review this, but significant changes during the year may also be worth checking.
11. Delaying a claim or failing to provide information
If something happens, check your policy for instructions on how and when to report it.
Insurers may require incidents to be reported promptly, particularly following theft, major damage or another event where evidence could be lost over time.
Where relevant, keep supporting information such as:
Photographs or video
Receipts or valuations
Details of damaged or stolen items
Contractor reports
Crime reference numbers
You should also take reasonable steps to prevent further damage where it is safe to do so.
A delay does not automatically mean a claim will be rejected, but it can make it harder for the insurer to investigate what happened.
12. Carrying out work that conflicts with policy conditions
Renovations, electrical work, plumbing or other alterations can sometimes create problems if the work does not meet requirements set out in your policy.
Poor or defective workmanship may itself be excluded, and whether resulting damage is covered will depend on the cause of the loss and your individual policy terms.
For major work, check what your insurer needs to know beforehand and make sure contractors are suitably competent and meet any relevant legal or policy-specific requirements.
Simply using a tradesperson without a particular accreditation does not automatically invalidate your home insurance.
Does a mistake automatically invalidate your home insurance?
No.
This is an important distinction.
If incorrect information was provided when the policy was arranged or changed, insurers must consider the nature of the misrepresentation and what they would have done had they been given the correct information.
Depending on the circumstances, an insurer might have:
Offered the same policy
Charged a different premium
Applied different terms
Declined to provide cover
For a qualifying careless misrepresentation, an insurer may in some circumstances apply different terms or settle a claim proportionately. Deliberate or reckless misrepresentation can have more serious consequences.
Other problems may simply mean that a particular type of loss is excluded or restricted rather than the entire policy being invalid.
Check your home insurance before you need it
Your property, belongings and circumstances can change significantly over time.
If you have recently carried out renovations, bought valuable possessions, started running a business from home, taken in a lodger or expect your property to be empty for an extended period, it is worth checking your insurance.
You should also review the amount of buildings and contents cover you have from time to time to make sure it remains suitable.
If you are unsure whether a change needs to be reported, check your policy documentation or contact your insurer or broker.
It is much easier to clarify your cover now than discover after a fire, flood, theft or other loss that something does not work in the way you expected.
Need to review your Grove & Dean Home Insurance?
If your circumstances have changed or you want to check your existing cover, you can review your Grove & Dean Home Insurance and contact us if you need assistance.
Find out more about Grove & Dean Home Insurance
Insurance cover, limits, conditions, exclusions and notification requirements vary by insurer and policy. Always check your policy documentation and contact your insurer or broker if you are unsure whether a change needs to be reported.


